Buy London property with the numbers in front of you.
We track rental yields, entry costs and letting demand across all 33 London boroughs, then show the working behind every figure. No listings pushed at you. No surcharge discovered three days before exchange. You get the same spreadsheet a buying agent would build, and you decide what to do with it.
Four things we do differently
Numbers before viewings
Most agency sites open with photographs. This one opens with a yield table. You see gross yield, entry cost and void assumptions for an area before any listing appears. If the maths fails, you have saved a flight.
Costs modelled to the pound
Stamp duty, the additional dwelling rate, the non-resident surcharge, legal fees, survey, furnishing and the letting fee. All of it lands in one figure, so your deposit calculation survives contact with reality.
Built for buyers outside the UK
Berkeley Square is our address, but most readers are in Dubai, Singapore, Lagos and Mumbai. Every process note assumes you cannot drop in for a viewing on Thursday afternoon.
The bit after completion
A flat sitting empty for four months returns nothing. We cover tenant demand, management fees, licensing rules and the boroughs where selective licensing will catch an absent landlord out.
Pick the route that matches your money
Three strategies dominate London buying right now. They need different budgets, different holding periods and different levels of attention after completion. Start with the one that fits, not the one with the nicest photographs.
Prime central resale
Mayfair, Belgravia, Kensington and Marylebone. Thin supply, low yields, and the strongest currency position for buyers holding dollars or dirhams. Read where prices actually sit before you assume a discount.
New build and off-plan
Nine Elms, Canada Water and Wembley Park. Staged payments and developer incentives read well on paper. Here is what to check before you commit a ten percent deposit to a building that does not exist yet.
Buy-to-let and management
Docklands, Stratford, Croydon and the outer boroughs. Higher yields, more tenant turnover, and licensing rules that change from one street to the next. This is the route that needs a real management plan.
The London market as it actually is
London property has spent the last decade doing two different things at once. Prime central postcodes have gone sideways in nominal terms since roughly 2015, while the outer boroughs and the commuter belt carried most of the price growth. If you only read headlines about record prices, you get the second story and miss the first one completely.
That split matters because it changes what you are actually buying. A flat in Belgravia has behaved like a currency position with a small income attached. A flat in Barking has behaved like a yield asset with modest capital growth on top. Same city, two different investments, and they respond to different pressures.
Everything below assumes you are buying to hold for at least five years. Short holds in London rarely survive the entry costs.
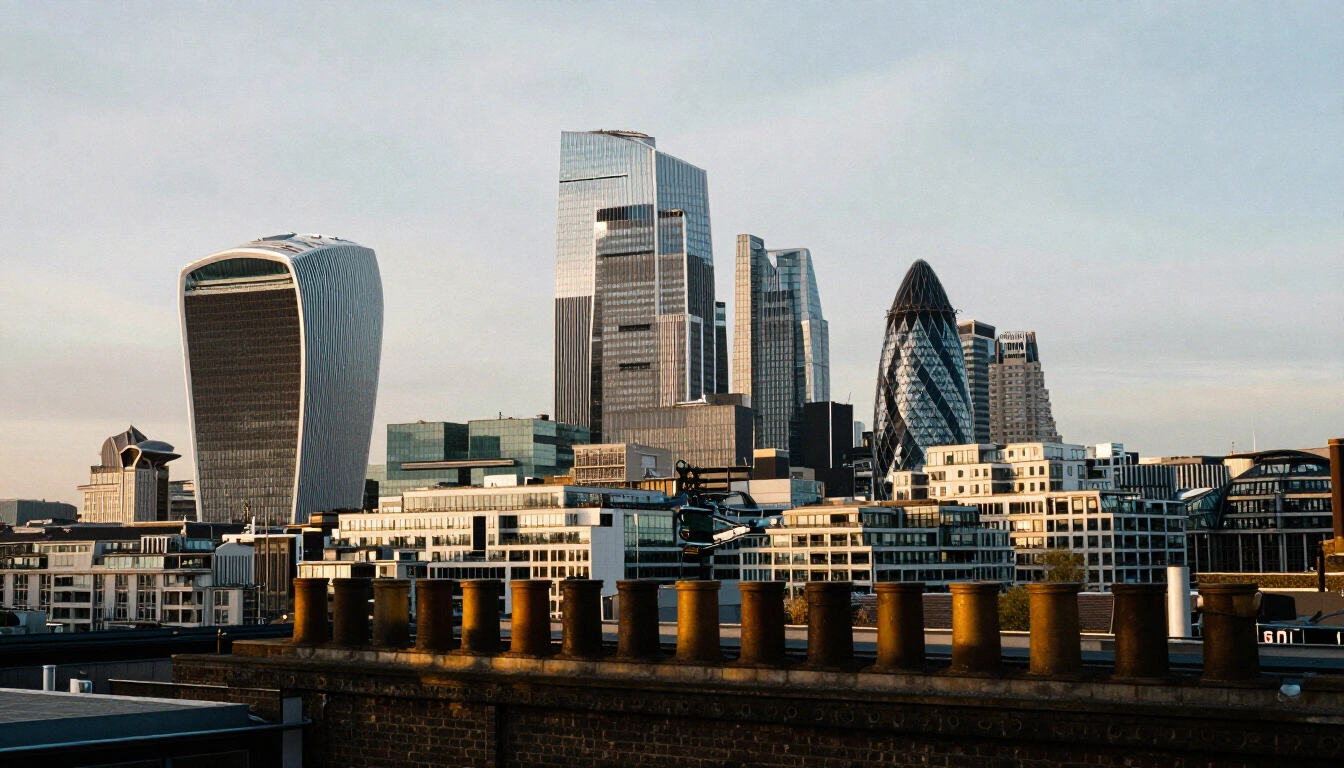
Prime central has been flat, and that is the point
Values in Mayfair, Belgravia, Knightsbridge and Chelsea peaked around 2014 and 2015, then took a long slide through successive stamp duty changes, the Brexit vote and the pandemic. Depending on the street and the index you read, prime central values in pound terms still sit below that peak.
Buyers holding dollars, dirhams or Swiss francs have had a very different experience. Sterling weakness did a lot of the work for them, and a market that looks flat in pounds can look like a sustained discount in another currency. That is the honest reason so much prime central buying is now international rather than domestic.
Here is the caveat nobody in an agency office volunteers. A currency discount is not a return. If sterling recovers while you hold, the same effect runs in reverse the day you sell and convert back. Treat the exchange rate as timing, not as the business case.
The yield map has inverted
Twenty years ago the received wisdom was that central London delivered capital growth and the suburbs delivered income. The income half of that is still true. The capital half is no longer reliable.
Gross yields in prime central sit near 3 percent and often below once the service charge lands. Move east and out, and 5 to 6 percent gross appears in Barking and Dagenham, Croydon, Newham and parts of Thamesmead. The gap between the two ends of London has widened rather than closed.
Gross is the wrong number to plan with. Take off ground rent and service charge, letting and management fees, insurance, an allowance for voids, and the maintenance you will actually spend rather than the maintenance you hope to spend. A 5.5 percent gross yield in an outer borough often lands near 3.5 percent net. A 3 percent gross yield in Kensington can land near 1.5 percent, which is the point at which you should ask what the flat is really for.
Rental supply is the real story
The rental side has been tight since 2021. A meaningful number of landlords left after the mortgage interest relief changes, the higher additional dwelling rates, and two years of rising costs on refinancing. Fewer rental homes chasing the same demand pushed rents up hard, then growth slowed as affordability caught up with tenants.
For a buyer today this cuts both ways. Letting a decent flat in a well connected postcode is usually quick. But tenants have become sharp about condition and about energy bills. A tired flat with a poor energy rating sits on the market while the refurbished one on the next street lets inside a week. Budget for the refurbishment before you budget for the return.
What the rate cycle did to the buyer pool
The rate cycle that started in 2022 priced a lot of leveraged domestic buyers out. Cash buyers and buyers with large deposits took a bigger share of transactions, which is part of the reason prime central held up better than the mortgage dependent middle of the market.
If you are borrowing, the sums are simply different from 2019. A 25 percent deposit is standard on non-resident buy-to-let products, expat rates carry a premium over high street residential, and lenders stress test the rent against the monthly payment before they lend. Run that stress test yourself, on paper, before you fall in love with a floor plan.
Transaction volumes tell the same story as prices. Fewer sales, longer time on market, and sellers who start high then negotiate. Asking prices in London are a starting position, not a valuation, and the gap between asking and achieved is where a prepared buyer makes money.
Where this leaves you
Two clean strategies exist and they do not mix. Buy prime central for capital preservation and currency exposure, accept the thin income, and hold for a long time. Or buy for income further out, accept that capital growth will be ordinary, and manage the asset properly.
The buyers who get hurt are the ones paying prime central prices while expecting outer borough yields. That expectation gap, far more than any market movement, produces the disappointed seller three years later. Decide which of the two you are before you look at a single listing, and write the decision down.
One honest limitation on everything above. Tax rates, surcharge levels and lending criteria change with every budget, and London is not one market but roughly thirty small ones that move at different speeds. Use these figures to frame the question, then confirm the current numbers with a solicitor and a broker before you commit money.
The 500,000 pound test: what five London zones actually return
Abstract yield talk helps nobody. So here is the same budget, half a million pounds, pointed at six different parts of London. Each row shows roughly what that money buys, the indicative gross yield range, the monthly rent it supports, how badly the service charge bites, and the kind of buyer the area suits.
Read the service charge column carefully. It is the line that quietly destroys returns in towers and in prime central mansion blocks, and it is the number most buyers check last.
| ZONE | WHAT 500K BUYS | GROSS YIELD | MONTHLY RENT | SERVICE CHARGE DRAG | SUITS |
|---|---|---|---|---|---|
| Prime central, W1 SW1 SW3 | Studio or a small one bed, often with a shorter lease | 2.8 to 3.4% | 1,200 to 1,400 | High, 3,000 to 6,000 a year | Capital preservation |
| Marylebone and Fitzrovia, W1U W1T | One bed in a period conversion | 3.4 to 4.0% | 1,450 to 1,650 | Medium, 1,800 to 3,200 a year | Long holds, low turnover |
| Canary Wharf and Docklands, E14 | One bed in a modern tower, occasionally a two bed | 4.4 to 5.2% | 1,850 to 2,150 | High, 3,500 to 5,500 a year | Corporate lets |
| Stratford and Newham, E15 E16 | Two bed new build, or a two bed conversion | 4.8 to 5.6% | 2,000 to 2,300 | Medium, 2,000 to 3,500 a year | Yield with some growth |
| Croydon and Barking, CR0 IG11 | Two bed with parking, sometimes a small three bed | 5.4 to 6.4% | 2,250 to 2,650 | Low to medium, 900 to 2,000 a year | Highest income |
| Richmond and Twickenham, TW1 TW9 | One bed period flat, garden access if you are lucky | 3.6 to 4.2% | 1,500 to 1,750 | Low, under 1,500 a year | Family tenants, short voids |
All figures in pounds sterling. Rent and yield ranges are planning estimates built from advertised rents against completed sale prices in each area, not quotes or valuations.
Three things this table will not tell you. It ignores voids, so knock roughly one month of rent off the annual figure in the outer boroughs and closer to two weeks in Richmond. It ignores management, which runs about 10 to 15 percent of rent for a fully managed service. And it ignores the ground rent and any major works bill sitting in the building’s five year plan, which is the single most common nasty surprise in a Docklands tower.
Run the same six rows with your own numbers before you shortlist anything. If the net figure still works after voids, management and a realistic maintenance line, the area is worth a viewing trip. If it does not, no amount of marble in the lobby will fix it.
Buying from outside the UK, step by step
The process itself is not complicated. What catches overseas buyers out is the order of operations. Do things in the wrong sequence and you either lose the property, or you lose four weeks waiting on a document that should have been ready in week one.
Here is the sequence that works, with the delays flagged where they actually happen rather than where the brochure says they might. Assume twelve to sixteen weeks from accepted offer to keys on a straightforward flat, and longer if a lease extension or a slow managing agent is involved.
Settle the money question before you look
Two things need to be true before you make an offer. Your funds need to sit somewhere a UK solicitor can accept them from, and the source of those funds needs documenting in a form a compliance officer will sign off.
Anti money laundering checks are the biggest single cause of delay for international buyers. A solicitor wants the origin of the money, not the balance. Proceeds from a named property sale with the completion statement attached. Dividends from a company you can evidence. An inheritance with the grant of probate. A screenshot of a bank app will not clear the file, and the firm cannot proceed until it does.
If you are borrowing, get an agreement in principle from a lender that genuinely does non-resident business before you view anything. High street residential pricing does not apply to you. Expect a 25 percent deposit minimum on buy-to-let products, a premium on the rate, and a stress test the rent has to pass.
Currency is the third piece and the one most people leave to the last week. Agree your transfer route early. A specialist broker usually beats a high street bank on a six figure transfer, and on a purchase of this size the spread between the two is not pocket change.
Instruct a solicitor before you find the property
Most buyers do this backwards. They find a flat, agree a price, then start hunting for a conveyancer, and the first fortnight vanishes into onboarding and identity checks while the seller wonders whether you are serious.
Instruct early instead. Hand the firm your identity documents and source of funds pack while you are still viewing. When the offer lands you want your solicitor raising enquiries on day two, not asking you to get a passport copy certified in another time zone.
Pick a firm that has actually done non-resident purchases. It is a specific skill set covering overseas identity verification, tax registration and sometimes power of attorney. A perfectly good local firm that has never handled one will be slow, and slow loses properties whenever there is a second bidder.
The offer, the memorandum, and the clock
An accepted offer in England and Wales binds nobody. Either side can walk away right up until exchange of contracts, and both sides do. Being outbid after acceptance is legal here, it has a name, and it still happens on anything genuinely good.
Once the offer is accepted the agent issues a memorandum of sale to both solicitors and the clock starts. Your solicitor orders searches, requests the leasehold management pack if it is a flat, and raises enquiries on the title.
The management pack is the usual bottleneck. Some managing agents take four to six weeks and charge a few hundred pounds for the privilege of waiting. Ask the estate agent on day one who the managing agent is and how long they typically take. A vague answer means you should budget for the long version.
Searches, survey, and the findings that kill deals
Local authority, drainage and environmental searches come as standard. On a leasehold flat you also want the remaining lease term, the ground rent structure, three years of service charge accounts, and any major works already voted through.
Three findings kill more deals than everything else combined. A lease under 80 years, because extending gets sharply more expensive once you cross that threshold. A major works bill in the tens of thousands sitting in the building’s forward plan. And fire safety or cladding paperwork that has not been signed off, which can leave a flat unmortgageable no matter how good it looks in person.
Commission a survey even on a new build. A level two report on a flat costs a few hundred pounds and regularly saves buyers many times that on the first defect it finds. Snagging lists on new developments are routinely long.
Exchange, completion, and doing it from abroad
At exchange you pay the deposit, usually 10 percent, and the contract becomes binding on both sides. Completion follows, often a fortnight later, sometimes on the same day if everyone wants it that way.
You do not need to be in the UK for any of it. Documents can be signed electronically or witnessed at a notary or your nearest British embassy, and funds move by transfer. Build extra days into the plan for anything that needs a wet signature posted internationally, because that is the step nobody remembers to allow time for.
One honest caveat on this whole section. The sequence is stable, the timings are not. A chain free purchase with a responsive managing agent can complete inside eight weeks. A leasehold flat with a slow freeholder and a lender that reprices halfway through can take five months. Plan for the long version and treat the short one as luck.
What these postcodes actually look like
Photographs will not tell you whether a purchase works. They will tell you what you are buying into, which matters a great deal when you cannot walk the street yourself. These six cover the full spread, from stucco Kensington at roughly 3 percent gross to a two bed behind Barking station at over 6. Look at the building stock, the street widths and the age of the housing, then go back to the table and match what you see against the numbers.
The true cost of owning a London flat
The purchase price is the number everyone quotes. It is also the least useful one. On a 500,000 pound London flat bought by a non-resident investor, the money leaving your account before you own anything can pass 60,000 pounds, and the annual running costs can take a fifth of the rent before any tax is due.
This section lists every line. Some will not apply to you. None of them should be a surprise the week you exchange.
Stamp duty, and the surcharges that stack
Stamp duty land tax works in bands. You pay a rising percentage on each slice of the price rather than one flat rate across the whole figure. On top of the standard bands, two separate surcharges can apply to you.
The additional dwellings surcharge applies if you will own more than one residential property anywhere in the world on the day the purchase completes. Note the anywhere. A flat you already own in Dubai or Mumbai counts. The non-resident surcharge applies separately if you have not spent enough days in the UK during the twelve months before completion.
They stack. A non-resident buying a London investment flat pays the standard banded rates plus both surcharges, and on a 500,000 purchase that combination is the largest single cost after the deposit itself.
Rates and thresholds move at almost every budget, and they have moved more than once in recent years. Have your solicitor produce the actual figure for your circumstances in writing before you exchange. Treat any online calculator, including anything on this page, as a planning tool rather than a quote.
What you pay on day one, beyond the price
Legal fees on a straightforward leasehold flat run roughly 1,500 to 3,000 pounds plus VAT, and sit at the higher end for non-resident files because of the extra compliance work. Searches add 300 to 500. The leasehold management pack adds 200 to 500. Land registry fees scale with the purchase price.
A survey on a flat costs 400 to 900 depending on depth. Mortgage arrangement fees on expat and non-resident products are often 1 to 2 percent of the loan rather than a flat figure, which on a 375,000 loan is real money. Currency conversion costs whatever spread you accept, which is exactly why you shop it.
Then furnishing. A one bed let furnished takes 4,000 to 8,000 pounds to do properly, and properly is not vanity. The photographs decide how quickly it lets, and a week of void costs more than a decent sofa.
The annual bills nobody puts in the brochure
Service charge is the big one on a flat and it varies wildly. A period conversion in Richmond might run 1,200 a year. A Canary Wharf tower with a concierge, a gym and a pool can pass 5,000. Against a 20,000 pound annual rent, that gap is close to a fifth of your income and it is fixed whether the flat is let or empty.
Ground rent applies on most existing leases, though the structure has changed for newer ones. Buildings insurance usually sits inside the service charge on a flat and is separate on a house. Landlord insurance covering liability and loss of rent is yours to arrange either way.
Letting fees run about 8 to 12 percent of rent for tenant find only, and 10 to 15 percent for a fully managed service. Add gas safety certification, electrical checks every five years, an energy performance certificate, and a selective licence in the boroughs that operate one. Licensing schemes differ by borough and sometimes by ward, so check the specific address rather than the borough name.
Maintenance is the line most spreadsheets leave out. Budget 1 percent of the property value a year and you will be roughly right across a decade, even though most individual years will be quieter and one will be brutal.
Tax on the rent, and tax when you sell
Rental income from UK property is taxable in the UK regardless of where you live. Non-resident landlords can apply to receive rent gross rather than having tax withheld at source by the agent, but you have to apply for it and you have to file a return either way.
Mortgage interest relief for individual landlords is now a basic rate tax credit rather than a deduction against income. That single change altered the maths considerably for higher rate taxpayers and is the main reason so many landlords now hold through limited companies. A company brings its own costs and reporting, and it is not automatically the better answer.
Capital gains tax applies to non-residents on disposals of UK residential property, and the reporting window after completion is short enough that people miss it. Inheritance tax exposure on UK situated property is a separate question again, and it catches a lot of overseas owners entirely off guard.
None of that is advice for your situation, and it should not be read as such. Rates, allowances and reliefs change, and the right ownership structure depends on your own tax residence and what else you own. Speak to an accountant who handles non-resident landlords before you buy rather than after.
A worked example on the Stratford row
Take the Stratford line from the comparison table. A 500,000 pound two bed let at 2,150 a month, so 25,800 a year gross. Service charge 2,600. Management at 12 percent, so 3,096. Insurance, safety checks and licensing, call it 900. Maintenance allowance at 1 percent of value, so 5,000. Void allowance of one month, 2,150.
That totals 13,746 in costs against 25,800 in rent, leaving 12,054 before any mortgage payment and before tax. Against the 500,000 purchase price that is a 2.4 percent net yield, set against the 5.2 percent gross a listing would advertise.
The number is not bad. It is simply less than half the headline, and it moves again once you add borrowing. Knowing that before you buy rather than in year two is the entire reason this page exists.
Ten minutes through the numbers
Reading a yield table is one thing. Watching someone build one is faster. This walkthrough takes a single 500,000 pound flat, prices the entry costs line by line, then models three years of ownership including one void period and one boiler replacement.
If you only have ten minutes, this covers the same ground as the two sections above it. Keep the comparison table open in another tab and follow along with your own budget rather than ours. The method matters more than the specific figures, because the figures will be out of date inside a year and the method will not. No sign up and no email gate.
Letting it, and keeping it let
Buying is a project with an end date. Letting is the part that runs for years, and it is where most overseas landlords quietly lose the return the spreadsheet promised them. A flat that lets in ten days at a fair rent beats a flat sitting empty for two months waiting on an optimistic number.
What follows are the decisions that arrive after completion, roughly in the order you will meet them.
Let only or fully managed
Let only means the agent finds a tenant, runs the referencing, draws up the tenancy and hands you the keys. Everything after that is yours for the next twelve months. It costs roughly 8 to 12 percent of the annual rent, usually taken as a lump sum at the start.
Fully managed adds rent collection, inspections, repairs, contractor coordination and the renewal negotiation. It runs about 10 to 15 percent of rent, charged monthly against the income.
If you live outside the UK, let only is usually a false economy. A boiler failing in January needs somebody who can be at the property that day and who has a plumber that answers the phone. From another time zone you will pay more for worse work, and the tenant will remember exactly how long it took.
The compliance list you cannot skip
A gas safety certificate every twelve months from a Gas Safe registered engineer, with a copy served on the tenant. An electrical installation condition report every five years. A valid energy performance certificate before you market the property at all. Working smoke alarms on every storey, and a carbon monoxide alarm in any room with a fuel burning appliance.
Deposits must be protected in a government approved scheme within 30 days, with the prescribed information served on the tenant. Get that wrong and you can lose the right to serve certain notices, on top of a penalty of up to three times the deposit.
Right to rent checks apply in England. Your agent should run them, but the liability stays with you as the landlord.
Licensing varies by borough, sometimes by street
London operates a patchwork rather than a single rule. Some boroughs require a licence for every private rented home inside a designated area. Others license only larger shared houses. The designated areas change on a schedule, and they sometimes cover named wards rather than the whole borough.
Check the actual postcode on the borough’s own licensing page before you complete, not the borough name and not a summary you found on a forum. Fees run into the hundreds and occasionally past a thousand pounds for the licence period. Letting without one where it is required carries a civil penalty and exposes you to a rent repayment order.
This is the single most common thing an absent landlord misses, because nobody writes to tell you about it.
Pricing the rent, and why the top of the range costs money
Agents quote a range. The temptation is to list at the top of it. The arithmetic argues against that nearly every time.
On a flat at 2,000 pounds a month, holding out for another 100 is 1,200 a year. Three extra weeks of void to get it costs about 1,385. You have lost money and acquired a tenant who knows they are paying above market and will negotiate hard at renewal.
Price at the middle of the range, let quickly, and put the energy into keeping a good tenant for three years. Turnover is the expensive event, not the rent level.
Arrears, and the realistic timeline
Most tenancies run without incident. When one does not, the process is slower than people expect. A notice period, then a court application, then a hearing date, then enforcement if it comes to that.
Several months from first missed payment to vacant possession is realistic, and the mortgage keeps falling due throughout. That gap is the risk, not the lost rent itself.
Rent guarantee insurance costs a few hundred pounds a year and covers the rent plus legal costs across that window. For a landlord who cannot fly in, it usually earns its premium. Read what voids the policy, because most require referencing to have been done to the insurer’s own standard.
What good management looks like from 5,000 miles away
Ask for three things before you sign with an agent. A named person rather than a general inbox. A written service standard on repair response times. And a portal where you can see statements, certificates and the current tenancy without emailing anybody.
Then ask two questions they will not expect. What was your average void period last year across the managed portfolio, and what percentage of tenants renewed. An agent who cannot answer either one is not measuring the things that decide your return.
The caveat, and it is a real one. Management quality varies enormously between branches of the same brand, and between individuals inside one branch. Judge the office and the person, not the logo on the window.
Straight answers, no sales pitch
These are the questions that arrive in our inbox most weeks, answered the way we would answer them on a call. Where the honest answer is that it depends on your circumstances, we say so rather than filling the space.
Can I buy a UK property if I do not live in the UK?
Yes. There is no restriction on foreign nationals or non-residents buying residential property in England and Wales, and you need neither a visa nor UK residency to own. What changes is the cost and the paperwork. You pay extra stamp duty, borrowing is harder and dearer, and checks on your source of funds take longer. Owning property here gives you no immigration rights of any kind.
How much deposit do I need as a non-resident buyer?
Plan on 25 percent as an absolute minimum for a non-resident buy-to-let mortgage. Thirty to thirty five percent is common depending on the lender, your country of residence and the currency you are paid in, and some lenders will not consider certain jurisdictions at all. Purchase costs sit on top of the deposit, so budget both in one figure rather than two.
What stamp duty does a non-resident investor pay?
The standard banded rates, plus the additional dwellings surcharge if you will own more than one residential property anywhere in the world at completion, plus the non-resident surcharge if you have not spent enough days in the UK over the preceding twelve months. Both surcharges can apply at once. Rates move at almost every budget, so get the current figure from your solicitor in writing before exchange.
Do I need a UK bank account to buy?
Not strictly, because funds can be sent to your solicitor directly from an overseas account. In practice a UK account makes everything after completion easier, including receiving rent, paying the service charge and setting up direct debits for utilities between tenancies. Opening one from abroad has become slower and can take several weeks, so start it early rather than in the week you complete.
How long does a purchase take from accepted offer?
Twelve to sixteen weeks is normal for a straightforward leasehold flat. Eight weeks is possible with a chain free seller and a responsive managing agent. Five months happens when the management pack is slow, a lease needs extending, or a lender reprices halfway through. Instructing your solicitor before you make the offer takes roughly two weeks off the front of that timeline.
Should I buy in my own name or through a limited company?
It depends on your tax position, how many properties you intend to hold and whether you are borrowing. Companies changed the mortgage interest picture for higher rate taxpayers, but they carry running costs, tighter lending and different rates. No single answer fits everyone. Settle this with an accountant who handles non-resident landlords before you offer, because changing your mind later means selling and buying again.
What is leasehold, and why does the lease length matter?
Most London flats are leasehold, meaning you own the property for a fixed term while a freeholder owns the building and the land beneath it. Below roughly 80 years remaining, extending gets markedly more expensive because an additional element enters the premium calculation. Lenders also turn cautious on short leases. Check the remaining term, the ground rent structure and three years of service charge history before offering.
Which London areas give the highest rental yields?
Generally the outer eastern and southern boroughs. Barking and Dagenham, Croydon, Newham and parts of Bexley regularly show gross yields above 5 percent against roughly 3 percent in prime central. Gross is not the whole picture. Compare net after service charge, management, voids and maintenance, because a high gross with a 5,000 pound service charge can finish behind a lower gross with a 1,200 pound one.
Do I pay UK tax on the rent if I live abroad?
Yes. UK rental income is taxable in the UK wherever you live. Under the non-resident landlord scheme your agent or tenant may have to withhold tax unless you apply to receive rent gross, and you file a return either way. Your country of residence may also tax the same income, with any double taxation treaty deciding the relief. Take advice covering both countries before you buy.
What happens if my tenant stops paying?
You serve the appropriate notice, and if the tenant does not leave you apply to the court for possession, wait for a hearing date, then instruct enforcement if it goes that far. Several months is a realistic span, and the mortgage keeps falling due throughout. Rent guarantee insurance covers rent and legal costs across that window for a few hundred pounds a year. Check the referencing conditions it requires.
Is off-plan safer or riskier than a completed flat?
Riskier in some respects and cheaper in others. You commit a deposit years before the building exists, so you carry completion risk, valuation risk if prices move, and the chance your mortgage offer expires before handover. In exchange you may get a lower price and staged payments. Check the developer’s delivery record, the long stop date in the contract, and what happens to your deposit if they miss it.
Send us the postcode. We will send back the maths.
One reply with the yield, the entry costs and the licensing position for the exact address you are looking at. No call booked, nothing sold to you, and no follow up sequence.
Written and maintained from Berkeley Square House, Berkeley Square, London. We track sale and letting evidence across all 33 London boroughs and rewrite this page whenever stamp duty, licensing or lending criteria move.
Every figure here is a planning estimate rather than a valuation, a quote or tax advice. Confirm your own numbers with a solicitor, a broker and an accountant before committing money.
Published 28 August 2026. Reviewed monthly.